There's a little-known tax law buried deep in the tax code, that most people blow right past without ever knowing it exists.
There's a specific tax law that applies to company stock held inside certain retirement plans. If your retirement plan holds actual shares of your employer's stock, this 2-minute check tells you whether it's worth a closer look before you roll that account into an IRA.
Start the 2-minute check →Two ways out of an employer plan full of company stock and most people may not ever hear about one of them.
When you leave a job, the default action is often rolling the entire employer plan — whether it's a 401(k), a profit-sharing plan or an ESOP — into an IRA. That's fine for people who do not have the same options.
How the company stock is moved out of the plan can significantly affect the later taxation of the shares...And that could keep more of your hard earned money from going to the IRS.
Roll it all to an IRA
A simple move for many people. Every dollar that eventually is withdrawn is taxed as ordinary income upon withdrawal.
Take the stock out a different way
The employer stock transfers in-kind to a regular brokerage account. The growth on those shares may later qualify for long-term capital gains rates, which are often lower than the ordinary income tax rates that growth would otherwise face.
Worth investigating before you roll over?
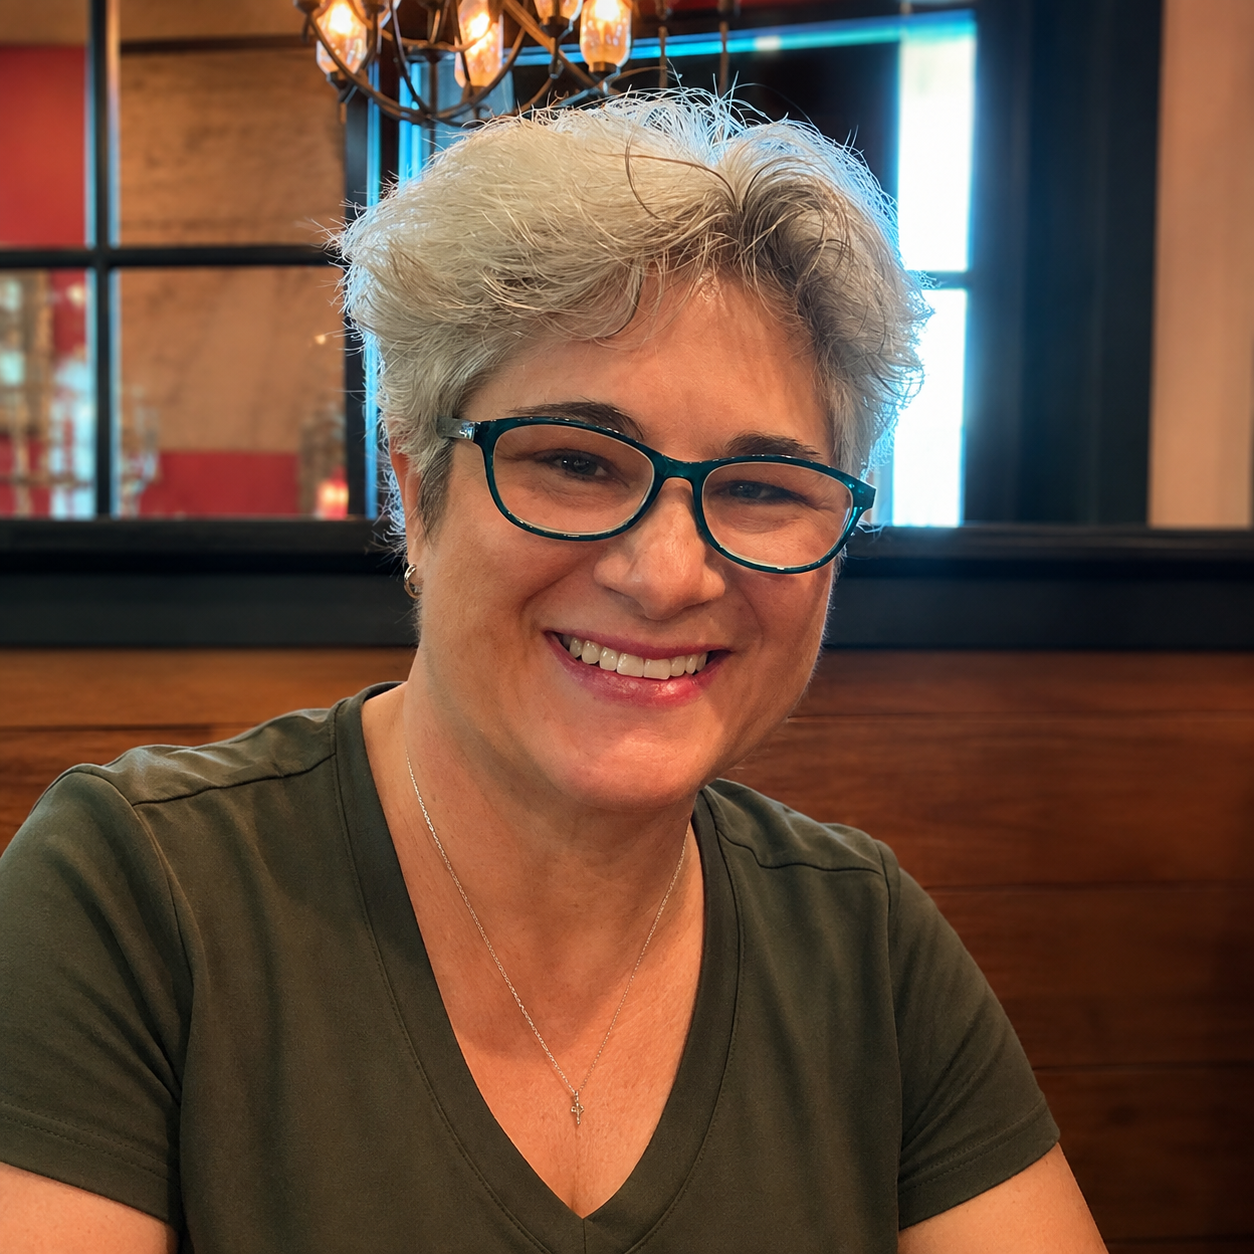
Not a bot, not a gatekeeper. Pam personally makes every call.
- 1Leave your name, email and phone below. It takes about 20 seconds.
- 2Pam usually calls within minutes. If she's not available immediately, she will call within the next hour or two. Her number is 864-884-8002, with caller ID as Pamela Harrison.
- 3You talk it through. The call is free, there's no obligation, and you can ask anything.
Questions people ask Pam
Answered in her own words. Tap a question to read the answer.Know someone this could help? Here's what a call with Pam is like, in her own words. Tap a question to read the answer.
About Pam
How long have you been a financial advisor?
I’ve been a financial advisor since 2004.
What credentials, designations or licenses do you hold?
I hold the Series 66 securities license, and I am registered as an Investment Advisor Representative, which allows me to provide fee-based financial planning, wealth management, and investment advice.
Why do you focus on company stock in retirement plans?
I began focusing on company stock in retirement plans after helping an employee explore his options as he approached retirement. Because he held company stock in his 401(k), we looked beyond simply leaving it in the plan or rolling it into an IRA. After finding an approach that fit his goals, he began referring colleagues with similar questions, and this area soon became a focus of my practice.
Roughly how many people have you helped look at company stock in their plan?
So many because coworkers have been referring their coworkers and this is now the sole practice in my business today.
Who do you typically work with?
I typically work with employees who are about to retire from a company that allows their employees to hold the company stock in a 401(k), an Employee Stock Ownership Plan and/or a Profit-Sharing Plan. I also work with small business owners, as I am one. Sometimes people who retire from the company go on to start a small business and they also refer me to those who have small businesses.
Is there anything personal you’re comfortable sharing?
I am very grateful for my life. I love playing guitar when the mood strikes; I love creating music. I love finding solutions to life’s questions, including financial solutions. I like reading the latest information as it develops, be it domestic or overseas, having to do with taxes or a mortgage and anything that may affect the stock market. I have a passion to make the space around me more beautiful and problem free.
After you request a call
What happens after I submit the form?
Once someone completes and submits the form, I usually call within minutes. If I’m not available immediately, I will call within the next hour or two.
What number will you call from, and will your name show on caller ID?
My number is 864-884-8002, with caller ID as Pamela Harrison.
What happens if I miss your call?
I understand people are busy and not able to talk when I call. I will leave a message and call one more time within the next 7 days. Thereafter, if I don’t hear from someone, I will assume they are no longer interested in seeking answers to their questions.
Do I need anything ready for the call?
Bring yourself and any additional information you wish to share on the call. You are welcome to have a simple Q&A or go into a deep dive conversation to answer whatever questions you may have.
The call itself
How long is the first call?
The call can last as long as you would like and no longer than 2 hours.
What do you typically ask about on the first call?
I like to ask about your financial situation. I like to find out as much information as you are willing to share with me to help me better understand who you are so that I may give the most precise answers I can.
What will you NOT do on the first call?
I am not a salesperson. I do not pressure anyone to do anything they are not ready or willing to do. I will only ask you if I have answered your questions, and what your next step or steps may be, if we haven’t already talked about that on the call.
Can my spouse, CPA or current advisor join the call?
Absolutely. You are welcome to bring your spouse or significant other, your CPA or tax advisor, your legal representative, your parent, and/or a child on the call with you. You may also bring your entire team with you.
What you walk away with
What will I walk away with after the first conversation, even if I never work with you?
The goal is to better help you to understand your situation, answer your questions and evaluate your options, and hopefully make your path easier to understand.
If it looks like a fit, what are the next steps?
That is completely up to you. Next steps usually involve follow-up conversations to talk about anything that could have been missed. I also talk about my process and what next steps I walk people through to be sure everything is covered. I would like to make sure that you are 100% ready to do business with me. The last thing anyone wants is regret or doubt.
If it’s not a fit, or the strategy doesn’t apply, what happens?
The call went well, and the caller walked away with answers to help them better prepare for their future.
How do you work alongside my CPA or tax advisor?
I can work with a CPA or tax advisor with us all together on a call, in person or with permission from you, at a meeting to help answer questions for you.
Cost and commitment
Is the first conversation free, with no obligation? Are there any conditions?
Yes. The first conversation and every conversation thereafter is free. You’re deciding whether I’m the right person to help you, and that decision should never be rushed. When someone calls me back to talk again before committing to anything, I consider that an honor because that may be your process. I enjoy speaking with people more than once, and as many times as they need. Until someone signs an agreement with me, there is no charge and no obligation at any time. Consultations are informative and educative.
If I become a client, how are you paid?
I am a fee-based advisor. Once someone becomes a client, there is an advisory agreement that we both sign where I get paid a fee, based on a percentage of your portfolio.
Does timing matter?
Timing can matter when evaluating distribution options involving employer stock in a retirement plan. Certain options may no longer be available after particular transactions occur, so it can be important to understand the alternatives and consult with appropriate tax and financial professionals before taking action.
Common concerns
What are the most common reasons people hesitate to talk with you?
Fear. People don’t call me because they don’t know me, and they’re afraid of sharing private information with me. It costs nothing to have a consultation, and you don’t have to share anything you are not comfortable sharing. There can also be some embarrassment. People don’t think they qualify. Rest assured, I never judge anyone, I’m only here to help.
What if I already have an advisor?
If someone says they already have an advisor, I ask, “What do you like about them?”, “What do you not like about them?”, “If you could change anything about your person or people, what would it be?”
Is this a sales call?
If they ask if this is a sales call, I say, “No. This is an information call.”
What if I’m not ready to do anything yet?
If someone is not ready to do anything yet, I ask, “how can I help you now?” There may be things people can do in advance of being ready to help them be even more prepared and ready when the time comes. Having a conversation and talking about your situation may bring solutions you never thought of.
What happens to my information?
Your information is never sold or put on any mailing list… ever.
Checking Pam’s background
How can I check your background?
Yes. Always look up the person you would like to do business with or even just talk to and share your information with. https://brokercheck.finra.org/ I am listed as Pamela S. Harrison, in Simpsonville, SC.
Still have a question? Ask Pam directly. It's free, and there's no obligation.
Request my call from Pam →If someone you know holds company stock in their retirement plan, a conversation with Pam before they roll it over could be worth their time.
A recommendation to roll over assets from an employer-sponsored retirement plan to an IRA should be based on the investor's individual circumstances and best interest. Before implementing a rollover, investors should carefully evaluate and compare the fees and expenses, investment options, services, distribution alternatives, withdrawal provisions, creditor protections, required minimum distribution rules, and other available benefits of their existing plan versus those available through an IRA. A rollover is not required and may not be in the investor's best interest in all circumstances. Other options may include leaving assets in the current employer plan (if permitted), transferring assets to a new employer's plan (if available), or taking a distribution. The Investment Adviser Representative and/or advisory firm may receive compensation or other economic benefits if assets are rolled to and managed in an IRA, creating a financial incentive to recommend a rollover. Accordingly, any rollover recommendation should be made only when the adviser reasonably believes it is in the client's best interest after considering costs, services, investment options, and reasonably available alternatives. This material is for informational purposes only and should not be construed as tax or legal advice. Investors should consult their tax and legal advisors regarding their specific circumstances.